It would be an understatement to say that active investing has been challenged in 2016. Political risks loomed large and the switch from deflation fears to reflation hopes in H2 led to sizeable trend reversals across the board. This took most investors by surprise.
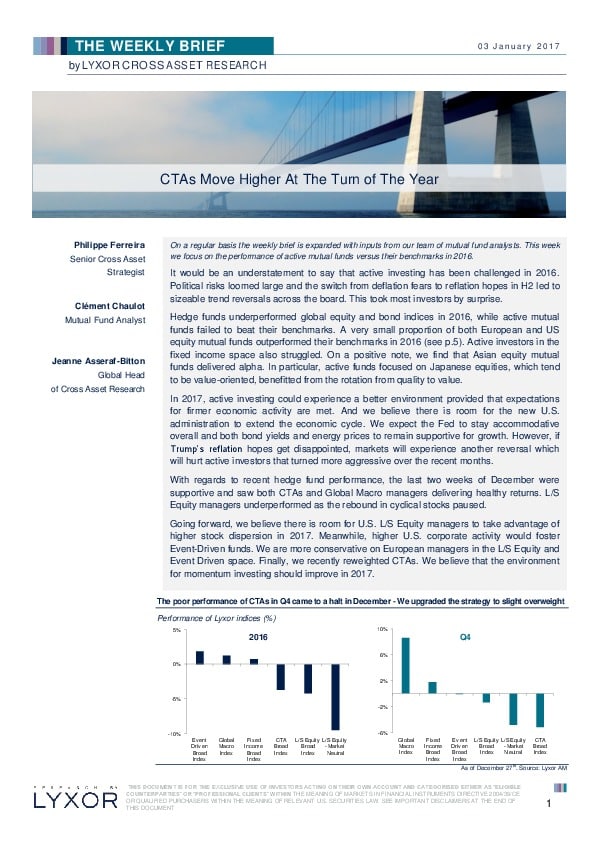
Hedge funds underperformed global equity and bond indices in 2016, while active mutual funds failed to beat their benchmarks. A very small proportion of both European and US equity mutual funds outperformed their benchmarks in 2016. Active investors in the fixed income space also struggled. On a positive note, we find that Asian equity mutual funds delivered alpha. In particular, active funds focused on Japanese equities, which tend to be value-oriented, benefitted from the rotation from quality to value.
In 2017, active investing could experience a better environment provided that expectations for firmer economic activity are met. And we believe there is room for the new U.S. administration to extend the economic cycle. We expect the Fed to stay accommodative overall and both bond yields and energy prices to remain supportive for growth. However, if Trump’s reflation hopes get disappointed, markets will experience another reversal which will hurt active investors that turned more aggressive over the recent months.
With regards to recent hedge fund performance, the last two weeks of December were supportive and saw both CTAs and Global Macro managers delivering healthy returns. L/S Equity managers underperformed as the rebound in cyclical stocks paused.
Going forward, we believe there is room for U.S. L/S Equity managers to take advantage of higher stock dispersion in 2017. Meanwhile, higher U.S. corporate activity would foster Event-Driven funds. We are more conservative on European managers in the L/S Equity and Event Driven space. Finally, we recently reweighted CTAs. We believe that the environment for momentum investing should improve in 2017.
The full report can be viewed here: Lyxor weekly Brief 3 January 2017
Picture: (c) mdd-shutterstock.com