

Insurance-linked investments offer something increasingly difficult to find in institutional portfolios: return drivers that are fundamentally different from those behind equities and bonds. At HedgeNordic’s recent ILS Day in Stockholm, Gustaf Hagerud, a former Alecta and AP1 allocator and former deputy CEO of AP3, argued that this distinction matters more than a low historical correlation coefficient, particularly when diversification is needed most.
For investors reconsidering the traditional 60/40 portfolio, adding another asset class does not necessarily mean adding another source of risk. Equity indices may contain hundreds or thousands of securities yet increasingly be dominated by a handful of companies. Credit, private equity, real estate and other seemingly distinct allocations can similarly retain substantial exposure to economic growth, financing conditions and interest rates.
For Gustaf Hagerud, CEO of Finserve Nordic and a previous allocator with around two decades of experience in strategic and tactical asset allocation at institutions including Alecta and AP1, this makes the distinction between statistical and fundamental diversification particularly important.
“When I say fundamentally uncorrelated, it is not just about looking at data, whether it is monthly data or daily data,” Hagerud told investors gathered at HedgeNordic’s ILS Day in Stockholm. “Rather, one should understand that what drives the return is uncorrelated with the stock market and the bond market.”
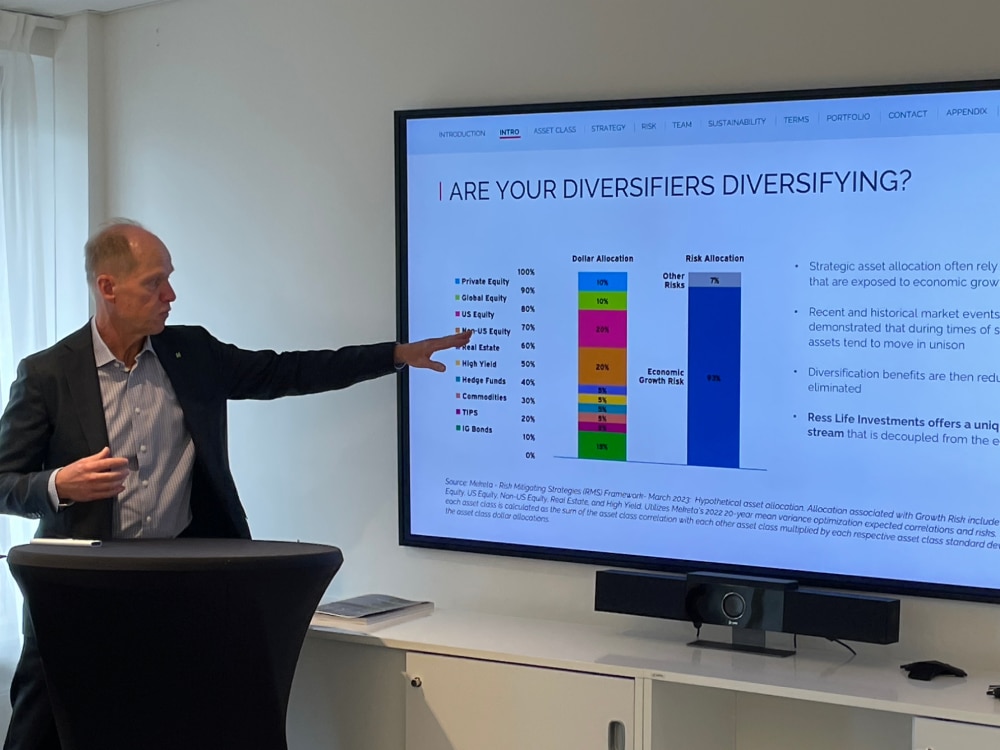
Hagerud identifies two dominant forces behind much of the return and risk in conventional financial assets: the global business cycle and monetary policy. Diversification becomes more meaningful, in his view, when investors introduce return streams whose underlying risks are not directly dependent on either. His presentation pointed to geopolitical tension, increasingly expansive fiscal policy, restrictive monetary policy and concentration in global equity markets as reasons for institutional investors to reconsider their allocation strategies.
His own interest in such return streams dates back to the global financial crisis. Starting a new role in September 2008, Hagerud recalled arriving just as “the entire portfolio fell out of bed.” The experience prompted a search for genuinely different sources of return. Insurance risk, including catastrophe risk and US life insurance, emerged among the candidates.
Different Risk, Not Simply More Risk
The attraction of insurance-linked investments in this context is not that they are riskless. Quite the opposite. Investors are explicitly accepting risks that other parties want to transfer. The distinction is what causes those risks to materialise.
In catastrophe bonds, investors provide capital against defined insurance events such as hurricanes and earthquakes. The insurance industry compensates investors for assuming severe risks that could otherwise place significant pressure on insurers’ balance sheets.
Life settlements approach insurance risk from almost the opposite direction. Investors acquire existing US life insurance policies from policyholders who no longer want or need them, continue paying the premiums and ultimately receive the insured amount when the policy matures.
The two strategies therefore involve very different risks, yet share an important portfolio characteristic: neither a hurricane making landfall nor the timing of an insured person’s death is directly determined by GDP growth, corporate earnings or central-bank policy. Hagerud’s presentation consequently describes the underlying risks of both strategies as fundamentally uncorrelated with the two primary risk factors he sees driving conventional financial assets.
Putting Diversification Into the Portfolio
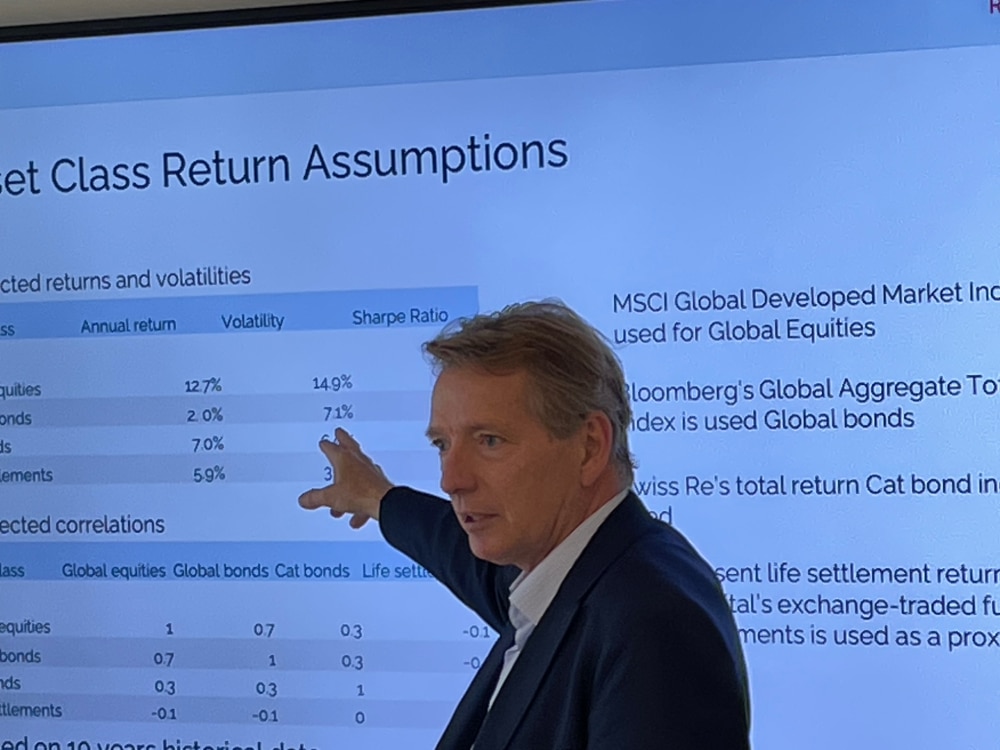
Hagerud illustrated the potential impact by starting with a conventional portfolio comprising 60 percent global equities and 40 percent global bonds. Using ten years of historical data to derive return, volatility and correlation assumptions, the traditional portfolio produced an expected annual return of 8.4 percent with expected volatility of 11.1 percent.
He then introduced insurance-linked investments while adjusting the equity and bond allocations so that the expected portfolio return remained unchanged. In one portfolio, a 20 percent allocation to catastrophe bonds reduced expected volatility from 11.1 percent to 9.6 percent. In another, ten percent was allocated to catastrophe bonds and ten percent to life settlements. Expected return again remained at 8.4 percent, while expected volatility declined further to 9.4 percent.
That represents a reduction in expected portfolio volatility of 13.3 percent and 15.3 percent respectively, without reducing the expected return in the exercise. But average volatility was only part of Hagerud’s argument. The more important test is what diversification does when conventional markets are under pressure.
“The interesting thing is to have diversification when the market goes down,” he said. An analysis prepared for a large Nordic institutional investor showed the insurance-linked allocations cushioning portfolio losses during periods including the Covid shock in the first quarter of 2020 and the market disruption following Russia’s invasion of Ukraine in 2022. “You should be strong when everyone else is weak,” Hagerud concluded.
The exercise also highlights why insurance risk need not be treated as one homogeneous allocation. Catastrophe bonds and life settlements have different underlying risks and different return characteristics. In Hagerud’s assumptions, their expected correlation with each other was zero. Cat bonds also tend to have shorter duration, while he characterised the observed volatility of life settlements as primarily being on the upside.
Catastrophe Risk: Beyond Cat Bonds
Cahal Doris, CIO ILS at Twelve Securis, took the discussion from portfolio theory into the catastrophe-risk market.
Cat bonds transfer defined insurance risks from insurers and reinsurers into capital markets. Investors provide fully collateralised protection and, in return, receive a floating cash return plus an insurance risk premium. Losses arise when specified insured events meet the contractual thresholds.
The return pattern therefore looks very different from that of conventional assets. Drawdowns are typically associated with insurance events – Hurricane Ian in 2022 or Hurricane Irma in 2017, for example – rather than recessions or changes in corporate earnings. Doris noted that the Swiss Re Cat Bond Index had returned around seven percent annually over the previous ten years, while the market itself has continued to grow.
For institutional investors, however, cat bonds represent only part of the opportunity. Twelve Securis also invests in private ILS, including privately negotiated reinsurance transactions. Combining the two can expand the range of risks available and allow managers to move between markets as relative pricing changes.
The trade-off is liquidity. Cat bond funds commonly offer weekly liquidity, whereas portfolios incorporating private ILS may move towards monthly liquidity. The underlying private contracts are generally short-dated, however, with Twelve Securis typically limiting them to around one year.
Asked how a first-time investor might choose between pure cat bonds and a broader ILS strategy, Doris therefore started with liquidity. “The first thought is liquidity,” he said. Investors seeking a return above what the cat bond market can currently provide may consider blending cat bonds with private ILS, but must be prepared to accept less liquidity in return.
The broader opportunity set can also improve diversification within the ILS allocation itself. Access to private transactions allows managers to spread exposure beyond heavily represented catastrophe regions and to exploit differences in pricing between the public cat bond and traditional reinsurance markets.
Longevity as a Return Driver
RESS Capital approaches insurance-linked investing from a very different direction. Co-Founder Jonas Mårtenson focuses on the US secondary market for life insurance policies. Policyholders who no longer want or need a policy can sell it to an investor rather than surrendering it to the insurance company. The investor acquires the policy, continues paying its premiums and ultimately receives the death benefit.
For the investor, the central uncertainty is longevity. If an insured person lives longer than expected, additional premiums have to be paid and receipt of the insured amount is pushed further into the future, reducing the investment return. If the policy matures earlier than expected, the opposite occurs.
That creates a return stream that is not only largely detached from corporate earnings and economic growth, but also fundamentally different from catastrophe risk. Mårtenson sees the two as complementary within an insurance-linked allocation.
“When you invest in cat bonds, you receive premiums, and then a hurricane strikes and you have an event taking place. In our case, it’s the opposite,” he explains. “We pay premiums for a life insurance policy, and when an event occurs, a policy payout, we have positive upside volatility. So it’s really two different return streams which are quite complementary.”
For Mårtenson, longevity is therefore at the heart of the diversification argument. Looking at RESS Capital’s listed fund over its 15-year history, he says: “There is basically no correlation to any asset class, which, when you think about longevity – how long will that individual live – doesn’t really have any huge correlation.”
Life settlements are not, however, entirely insulated from financial-market conditions. Interest rates affect the present value of their long-dated cash flows and have influenced secondary-market pricing in recent years. RESS has responded by selling a substantial portion of its older portfolio and reinvesting the proceeds into newly acquired policies offering higher prospective returns. Mårtenson currently sees projected gross IRRs of approximately 15 to 20 percent on new purchases and targets a net return of around ten percent over the coming five years. These are prospective estimates rather than guaranteed returns.
The structure of the return stream is also unusual. Rather than experiencing a negative shock when an insured event occurs, as can happen with catastrophe bonds, a life-settlement portfolio receives its cash flow when a policy matures. “The volatility is much more on the upside,” says Mårtenson. “When a policy pays out, the net asset value may increase in a single month by one or two percent.” He consequently views life settlements as a medium- to long-term allocation, noting that some RESS investors have remained invested for more than a decade.
