

By Harold de Boer at Transtrend: Cows produce milk. Every day again. That’s the fixed income for the dairy farmer. Bulls don’t produce milk. Yet, equity investors prefer bull markets. Until they crash.
The farmer combines them. Bulls reproduce the cows that produce the milk. Although a productive herd does not require anything close to a 60/40 split, a mixture of cows and bulls generally brings prosperity. Until their shared pasture is buried under hard-packed snow or withers in a prolonged drought.
Then the commodity trader enters the field. Add crops to the portfolio! For the average investor, this sounds unnecessarily complicated. There is grass to feed the cattle. There always has been. There always will be. Or so they assume. Only the more willingly aware dare not to count on that.
With this complexity come the quants. They relentlessly impress with stats proving how much less we will be hit by historical stock market sell-offs if we spread our investments over different mixtures of stocks and bonds. Or even better, mixtures of stocks and bonds and CTA-trend: 60/40, 50/25/25, 60/0/40 or even 75/0/50.
You name it, the quant produces the numbers. And let’s be honest, such numbers feel more objective and surely more sophisticated than an obscure story about cows, bulls and feed. But every real quant can explain why, statistically, these numbers are not as solid as they appear. They assume that different historical stock market crashes are different observations drawn from the same stochastic process. In the absence of properly determined causality, such numbers are just numbers. They have no predictive value. So, it is better not to count on them. Instead, let’s look at the foundation of the 60/40 success.
A few years ago, I was invited to give a lecture for a group of students. They essentially wanted to hear what they should do to be able to stop working at an early age. A good preparation starts in time, so in that sense these mostly still teenagers were off to a good start. I explained that there was no single way to accomplish that; historically every generation had found its own way. When specifically asked about the strategy of my generation, I told them that this was supposed to be kept secret. But I was willing to reveal it to them under the condition that they would not tell anyone else. So they promised.
Since most of the readers of this piece will be part of my generation, I can write the same story here. Any younger readers are kindly requested to skip straight to the last two paragraphs.
General debt and free-floated market cap in tn USD
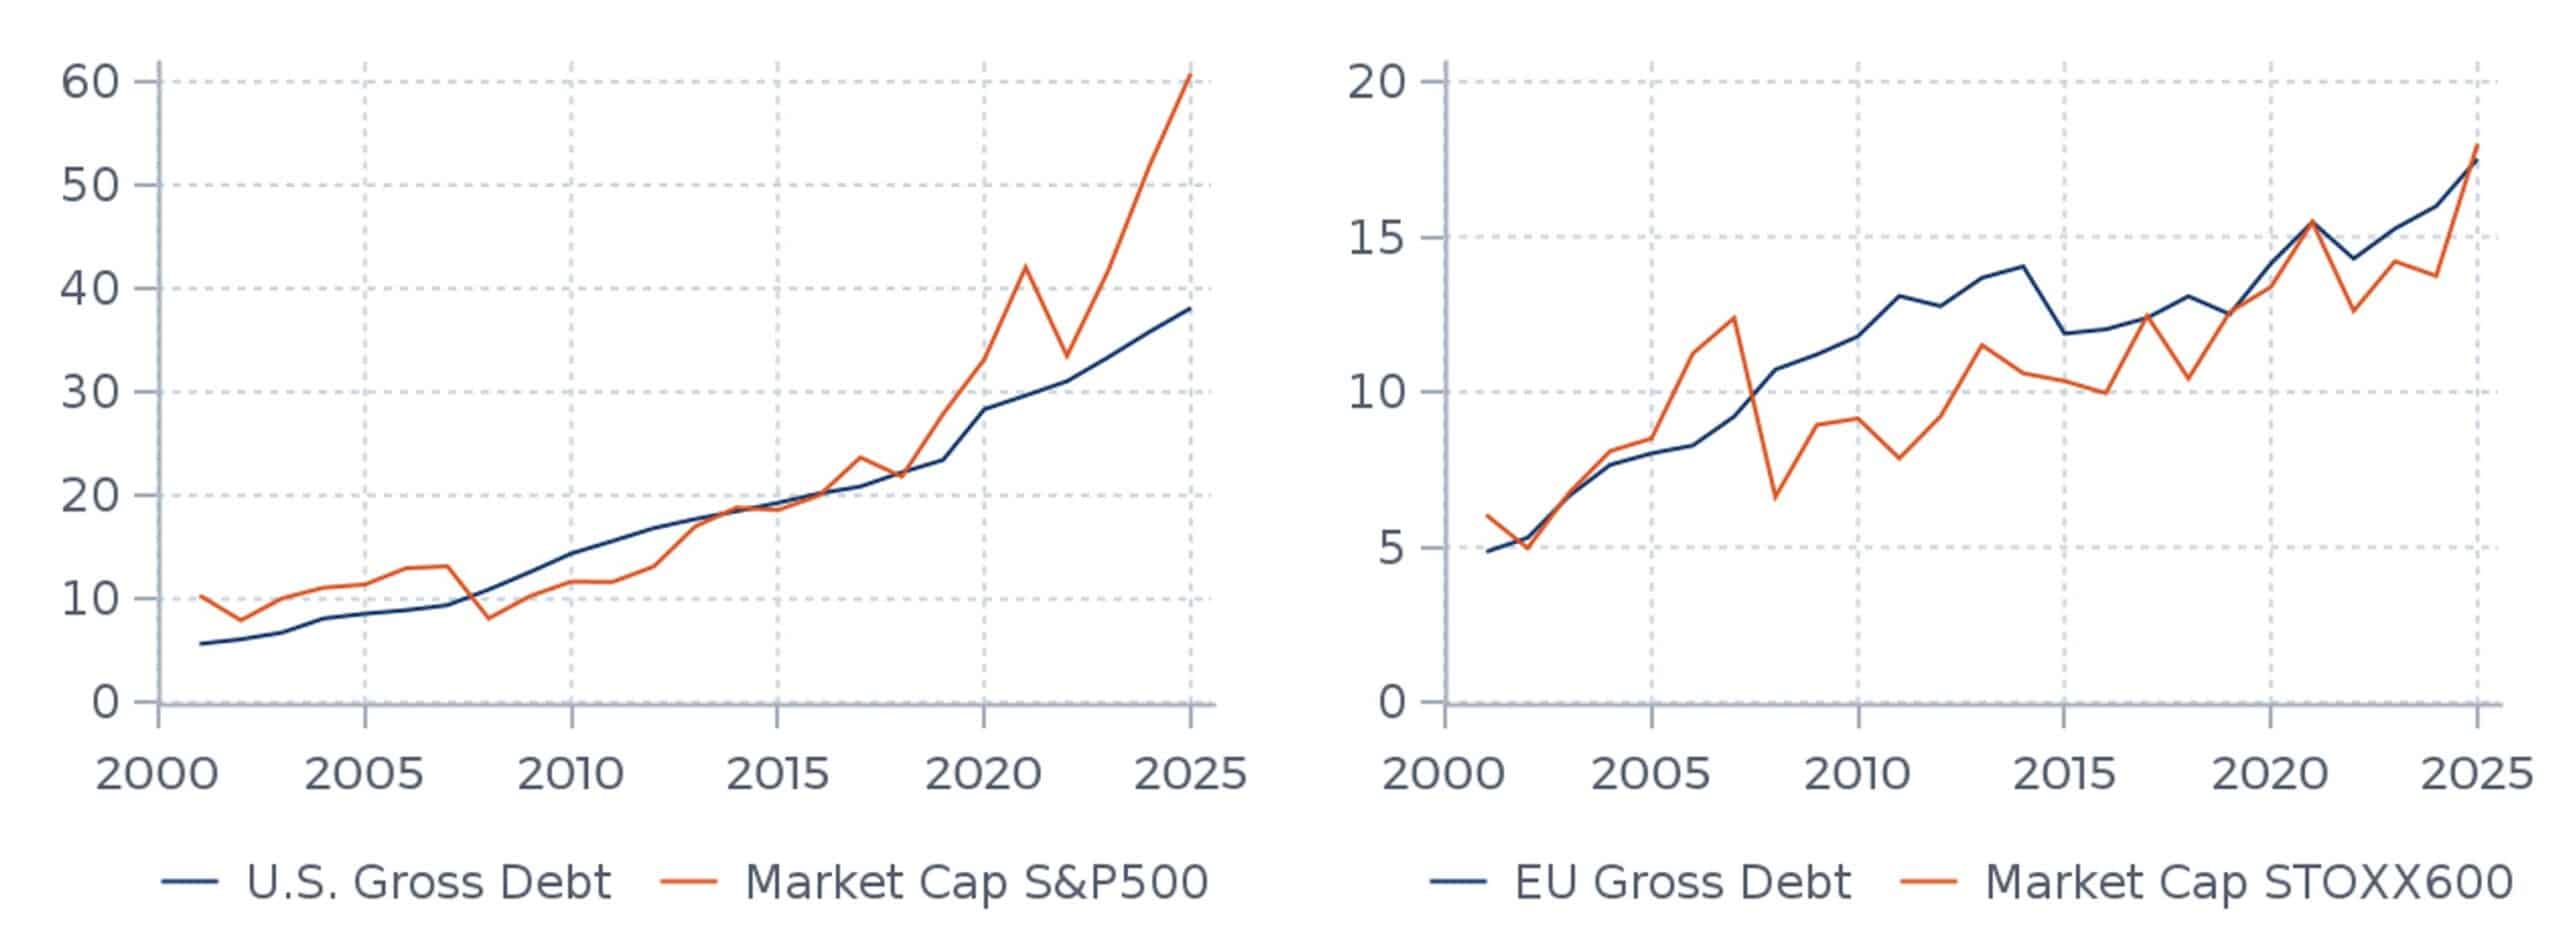
My explanation started by showing an earlier version of the chart above. It shows the stock market value and the government debt in the United States. The European picture is not fundamentally different. Another part of the world; the same generation.
Our generation has massively invested in stocks. As a result, the value of stocks has gone up, providing the capital for our pensions. Our cunning trick is this: we did not invest our own capital. We borrowed the money. Or more precisely, our governments did. We have organized a convenient scheme, according to which our government spends more on us, on the various things our society needs, than we return to our government through taxes. This has resulted in explosively grown government debts. The official story is that all these government expenses have been used to build our societies and support our economies. In this story we use the grown stock market cap as proof of our economic success. But the true story is that we have grown our personal wealth at the expense of the next generation. We borrowed; our children and grandchildren will have to repay it. Or they must find another trick. That is up to them.
Our scheme is quite artfully constructed. Every time we encounter adversity that causes stocks to fall, our governments respond by borrowing more money to support the economy and/or our central banks respond by cutting interest rates, causing bond prices to rise. This essentially is the grass that feeds our 60/40 stocks/bonds strategy.
A recent example was the COVID pandemic. Many people were surprised how fast stock markets recovered from the initial sell-off. But to us that was no surprise. It was part of my generation’s strategy. Our governments flooded society with support, officially meant to help us and our companies survive the lock-downs. But effectively it was used to save our capital. A lot of that money was used to invest. My generation benefited from that again. And the debt will be passed on to our descendants. They inherit it.
Somehow, not all students were enthusiastic about my generation’s strategy. One of them even mentioned a flaw. He said: “Your pension is dependent on us buying your stocks for their present value. What if we don’t buy those stocks, but prefer to invest in other companies? What if we start new companies?” I replied that this is precisely why our generation so passionately advocates passive investing. To make sure that our children spend most of their money on exactly those stocks on which we have already spent most of their money.
But the message is clear. The ongoing success of our scheme, including the ongoing success of the 60/40 passive long stocks and bonds, is not dependent on its historical success. It depends fully on the willingness of the future, and increasingly already present, generation to keep executing it. Why would they?
If we look back at stock market sell-offs over the last 50-plus years, we recognize a common denominator: many of them represent the bursting of a bubble. Could the current situation, a huge stock market cap founded on huge government debts, turn out to be a bubble too? If it implodes, will losses in stocks again be partially compensated by profits on the ”safe haven” bonds? We would not count on that.
In fact, we already experienced a situation like this after the COVID crisis. In 2022, falling stocks coincided with falling bonds. CTA-trend programs including Transtrend’s Diversified Trend Program performed very well during that period, profiting from trends in, among other things, commodities. Will our program automatically do the same the next time stocks and bonds fall together? We do not count on that. It again will require active management. A crucial element of our program is that we do not seek comfort in the past. Time and again, history takes a turn. We’ve learned to count on that.
This article is part of HedgeNordic’s “Rethinking the 60/40 Portfolio” publication.
