
- Advertisement -

Related

Are We in for a Soft Landing?

- Advertisement -

 The Federal Reserve (the Fed) has undoubtedly caused many U.S. recessions over time when attempting to fight inflation through tighter monetary policy. However, sometimes it has engineered so-called “soft landings” whereby inflation slows and real growth continues. How likely is a soft landing in this cycle? 
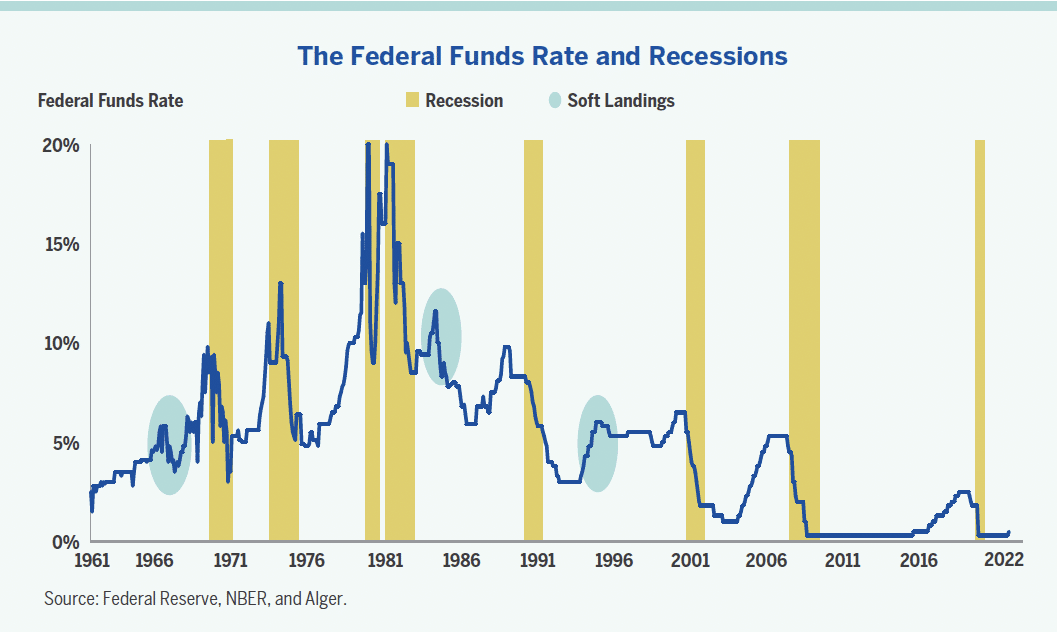
 As shown above, most of the times when the Federal Funds rate rises, a recession follows – “hard landings.” However, the circled areas show when the Federal Reserve raised interest rates, but a recession did not follow – “soft landings.” 

In all three cases, the Fed tightened 300 basis points or more, but economic growth continued. That amount of tightening is about what is anticipated by the Fed’s own projections released in March. Note that the Fed also tightened materially from 2015 to 2018 with the economy growing solidly in 2019, only to be upended by the pandemic. 

At a time when the Fed appears to be increasingly hawkish on inflation, it may be comforting to know that monetary tightening doesn’t always lead to recession and that soft landings have been kind to investors in recent history. Indeed, in the 12-months following the end of Fed tightening in 1985 and 1995 as well as after the Fed relented in 2018, equities generated double-digit returns. 


A piece written by Alger – a La Française partner firm. La Française AM Finance Services, in accordance with the terms of an agreement signed with Alger Management, Ltd, is a distributor of the Alger SICAV in Europe.


Title Pic by pixabay.com

Subscribe to HedgeBrev, HedgeNordic’s weekly newsletter, and never miss the latest news!

Our newsletter is sent once a week, every Friday.

HedgeNordic Editorial Team
This article was written, or published, by the HedgeNordic editorial team.

Latest Articles

Simplicity Completes Norron Deal

Three months after announcing the deal, Swedish asset manager Simplicity has completed its acquisition of Norron’s fund management business, taking over the management of...

Rethinking the 60/40 Portfolio

The 60/40 portfolio remains one of investing’s most recognizable conventions, even where few institutional portfolios literally consist of 60 percent equities and 40 percent...

Diversification That Comes From Somewhere Else

Insurance-linked investments offer something increasingly difficult to find in institutional portfolios: return drivers that are fundamentally different from those behind equities and bonds. At...

Reinforce, Don’t Replace: Carrying the 60/40 Through the Fragile Decade

By Steven Braun at Newfound Research and Return Stacked® Portfolio Solutions: Despite its ambiguous origins, the 60/40 remains the default portfolio for investors approaching...

Varma: Practical Considerations for Embracing a Total Portfolio View

Finland’s Varma is one of several large Nordic asset owners that has been moving towards a more holistic view of the portfolio – some...

Thinking Outside the 60/40 Box: How Active and Dynamic Commodities Can Complement Bonds

Bonds helped investors to diversify equity between about 2000 and 2021, which more than covers the entire career of many allocators. Since 2022 bonds...

Allocator Interviews

- Advertisement -

Voices

Request for Proposal

- Advertisement -